

Each statement explains:
- Public Liability Insurance – physical events; someone gets hurt, or some property is damaged due to your business activities.
- Professional Indemnity Insurance – financial events; your client incurs a financial loss due to a mistake or omission in your professional advice or service.
These two types of insurance respond to fundamentally different triggers. PL is activated by a physical incident. PI is activated by a professional failure. Understanding this distinction determines which cover type, or whether both, is needed for a specific business, and it is usually the first thing worth clarifying before comparing quotes for either one.
The Core Distinction in Plain Language
One sentence each: public liability insurance covers physical events, someone is hurt or something is broken as a result of your business operations. Professional indemnity insurance covers financial events, a client suffers a financial loss because of an error or omission in your professional advice or work.
These two types of insurance respond to fundamentally different triggers. PL is activated by a physical incident. PI is activated by a professional failure. Understanding this distinction determines which cover type, or whether both, is needed for a specific business, and it is usually the first thing worth clarifying before comparing quotes for either one.
Get a PL and PI insurance quote
once you know which trigger applies to your business.
What Public Liability Insurance Covers
- Bodily injury to customers, visitors, or members of the public caused by business operations or negligence
- Damage to the property of third parties through accident while doing business
- Defence costs for legal proceedings due to claims of injury or damage
- Settlements made and damages awarded by the court
What PL does not cover: professional errors or advice-related losses, which fall under PI; employee injuries, which fall under COIDA; intentional damage, and contractual liability beyond what the law already imposes.
What Professional Indemnity Insurance Covers
- Negligent professional advice or recommendations that cause a client financial loss
- Errors or omissions in professional work, reports, designs, or deliverables
- Failure to meet the professional standard expected in the engagement
- Legal defence costs, including when a claim is ultimately unfounded
- Damages and settlements awarded against the professional
What PI does not cover: physical injury or property damage to third parties, which falls under PL, employee claims, intentional wrongdoing, fraud, and claims arising before the policy’s retroactive date.
Side-by-Side Comparison
|
Factor |
Public Liability |
Professional Indemnity |
|
Trigger |
Physical injury or property damage to a third party |
Financial loss from professional error or negligence |
|
Type of claim |
Personal injury, medical costs, property damage |
Economic loss, failed professional services |
|
Who claims |
Customers, visitors, members of the public |
Clients who relied on professional work or advice |
|
Who needs it |
Any business interacting with the public |
Professionals providing advice or services for a fee |
|
Legally compulsory? |
Not universally, required by leases and tenders |
Yes for FSPs under FAIS and attorneys under the LPC |
|
Common indemnity limits |
R1m to R10m |
R1m to R10m |
|
Combined policy available? |
Yes, some insurers offer PL and PI together |
Yes, some insurers offer PL and PI together |
Everyday Scenarios: PL, PI, and Both at Once
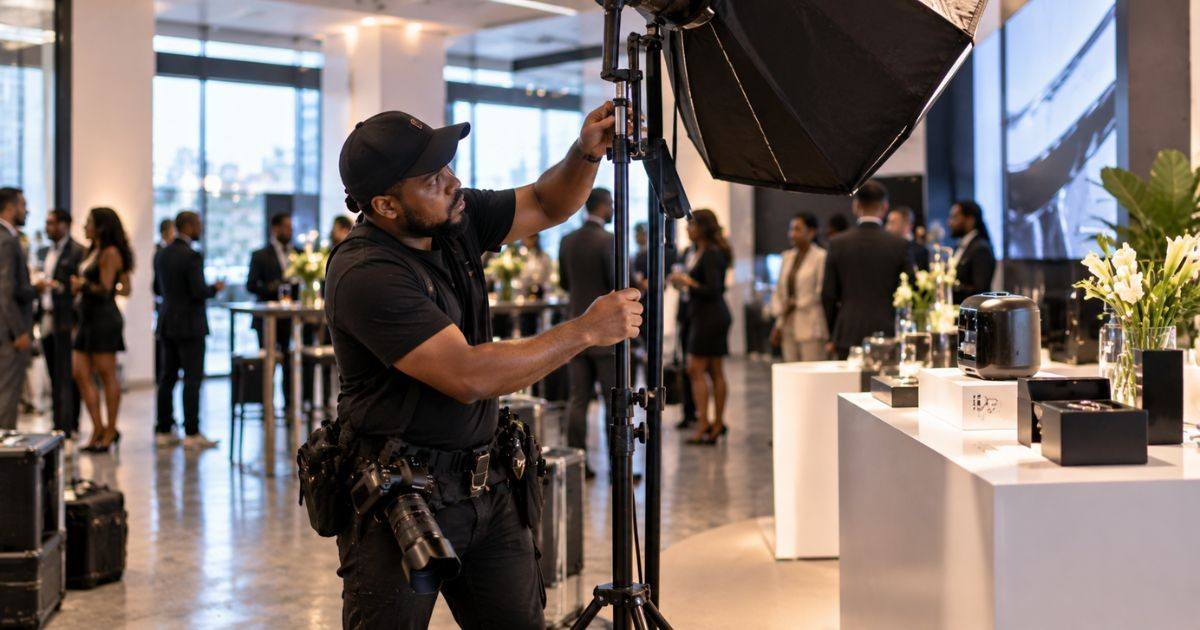
- PL scenario: an event photographer uses his lights at a client’s product launch. His stand falls and causes damage to the client’s display goods. The client makes a claim for the costs incurred in replacing the damaged goods. This is a PL claim because there was no professional negligence.
- PI scenario: an accountant advises a client on a specific tax structuring approach. The advice turns out to be incorrect, and SARS raises a penalty assessment against the client. The client claims against the accountant for the resulting loss. This is a PI claim: financial loss arising purely from professional advice, with no physical incident at all.
- Both in the same engagement: an IT consultant is on site installing a system upgrade. While working, the consultant knocks over and damages a server rack, a PL claim, and separately configures the system incorrectly in a way that causes the client to lose several days of sales data, a PI claim. Both policies are triggered by the same site visit, on the same day.
That last scenario is the one worth paying attention to, since it shows how a single piece of work can generate two completely different types of claims at once, each requiring a different policy to respond.
Compare PL and PI insurance options today
and see where your own business fits.
Which Businesses Need Both PL and PI?
- Needs PL: When the business is physically interacting with customers or the general public, working out of other locations or having its premises accessible to the outside world.
- Needs PI: When the business is rendering professional advice, specialized services or professional outputs to the clients.
- Needs both: Any business that does both, which is the case for most professional services businesses that also interact physically with clients.
Examples that typically need both: architects, engineers, management consultants, IT service providers, accountants, estate agents, and healthcare practitioners. Examples that may need only PL: retail stores, restaurant operators, and event organisers. Examples that may need only PI: online-only consultants with no physical client interaction at all.
Can PL and PI Be Combined Into One Policy?
Yes, in some cases. Some South African insurers offer combined professional liability policies that include both PL and PI under a single contract, renewal date, and premium. This simplifies administration and may offer a modest cost saving compared with arranging both separately.
The key consideration for combined policies is confirming that the indemnity limit applies separately to PL and PI claims, rather than as a shared aggregate limit. A shared limit that can be fully consumed by one large PI claim leaves the business without PL cover for the rest of the policy year, which defeats much of the point of holding both.
Which Is More Important?
Neither is universally more important. The priority depends on the business’s primary risk exposure:
- For businesses with high physical client interaction, such as retail, hospitality, or tradespeople: PL is the primary priority.
- For businesses providing professional advice or services with limited physical client interaction: PI is the primary priority.
- For most professional services businesses that do both: both are essential, and neither should be deferred indefinitely.
Important: if money is an issue, and only one insurance can be purchased at a time, then the type of cover which should be prioritized would be the one that deals with the most probable and most expensive risk associated with the particular business.
Ready to get the right combination in place?
Get the right business liability cover for your business.
Frequently Asked Questions
Does public liability insurance cover professional mistakes?
No. Public liability responds to physical injury or property damage, not financial loss arising from professional advice or work. A professional negligence claim, such as an incorrect design or bad advice, falls under professional indemnity instead, even if the underlying incident happened at a client’s physical premises.
Is professional indemnity more expensive than public liability?
It is highly dependent on the professional and the risk profile of the business concerned rather than being a hard-and-fast rule. Professional indemnity insurance for higher-risk professions such as providing legal or financial advice tends to be costlier than contractor’s insurance for a similar business, but PL insurance for a consultant’s higher-risk contractor may well be higher than professional indemnity insurance for a lower-risk consultant. Obtain a quote for your particular business instead.
Can I get a single policy that covers both PL and PI in South Africa?
Yes, certain insurance providers provide professional liability insurance that combines both. Make sure you know the limits provided by each type of cover in the combined policy, as otherwise, the combined limit would provide lower coverage than one might expect if the entire limit was used by one kind of claim.
Which do I need first: public liability or professional indemnity?
Whichever addresses your business’s more immediate and significant exposure. A business regularly on client sites or interacting with the public in person should generally prioritise PL first. A business whose main activity is giving advice remotely, with limited physical client contact, should generally prioritise PI first.
Does public liability cover damage I cause at a client's premises?
Yes, provided the business’s act is accidental and arises from the business’s operations rather than from a professional error in the client’s work itself. Accidentally breaking a client’s equipment while on site is typically a PL matter. Giving advice that later proves financially costly to the client is a PI matter, even if it happened during the same visit.
Last reviewed: September 2026. This guide is reviewed periodically to reflect current South African insurance and professional regulation. Financial services providers are regulated under the FAIS Act 37 of 2002 by the FSCA, and attorneys by the Legal Practice Council. Employee injury compensation falls under COIDA, separate from public liability cover. Insurance conduct generally is governed by the Insurance Act 18 of 2017.
This article is part of our complete public liability insurance guide for South African businesses and our complete professional indemnity insurance guide. For the basics of PL, see what is public liability insurance, and for a full application walkthrough, see how to get public liability insurance. For the PI perspective on this same comparison, see professional indemnity vs public liability insurance, and if you are still deciding whether PI applies to you, see who needs professional indemnity insurance. See our About page or Privacy Policy.

0 Comments